
FolderDesa brings together practical knowledge on farming, village-owned enterprises, culinary traditions, rural tourism, and small-business ideas — all rooted in the everyday life of Indonesian villages.
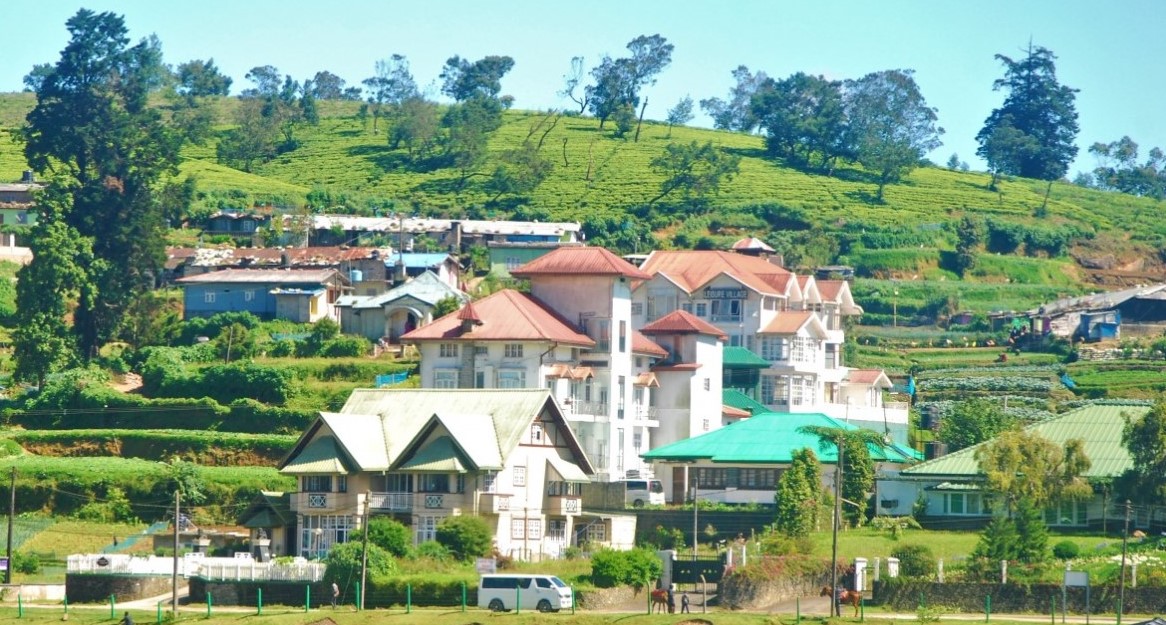
"From taro cultivation in Bogor to village tourism in Banyumas, every village has a story worth telling — and an opportunity worth sharing."
Seven areas of village knowledge
FolderDesa organizes its articles across these interconnected topics, each one grounded in real Indonesian village experience.
What you'll find on FolderDesa
Practical articles written by contributors who understand village life.
Agriculture & Cultivation
Articles on taro (talas bogor), dragon fruit, crystal guava, durian, oyster mushrooms, and tabulampot grapes — plus livestock such as dairy goats and Merino sheep.
Village-Owned Enterprises
Guides on establishing BUMDes, the differences from cooperatives, and why professional phased management matters for village economic growth.
Village Tourism
Coverage of destinations like Desa Karangkemiri in Banyumas, where outbound activities and a swimming pool helped tourism contribute Rp 50 million to village income in 2021.
Culinary Traditions
Indonesian village foods, Sundanese heritage dishes, spiced drinks, infused waters, seafood street-food ideas, and home-industry snack production.
Business Opportunities
From dried wood ear mushrooms and kopyor coconut seedlings to ecoprint crafting, bamboo crafts, and mina padi integrated rice-fish farming.
Village News & Community
Reports on social assistance programs like PKH, village governance structures, and practical tips such as safe homecoming travel during mudik season.
Village savings and loan groups: a practical handbook
A village savings and loan group can turn small, regular contributions into useful capital for farming, household needs, and local enterprise. In Indonesia, these groups are often known as kelompok simpan pinjam and may operate through a hamlet, women’s association, farmer group, cooperative, or village-owned enterprise (BUMDes).
The model is simple, but successful groups depend on clear rules. Members save according to an agreed schedule, borrow from the shared fund, repay with a fair service fee, and review the records together. The process creates access to finance while strengthening trust and cooperation within the community.
This handbook explains how to establish a village savings group, assess borrowers, manage records, and protect the fund from common problems. It is designed for residents, farmer organizations, village officials, and local entrepreneurs who want a practical system rather than complicated financial products.
Define the group’s purpose
Start by agreeing on the main purpose of the group. A savings and loan association may support seasonal farm inputs, livestock, school expenses, emergency health costs, home-based businesses, or small trading activities. A clear purpose helps members decide how much to save and which loans deserve priority.
Membership should be based on a real connection, such as living in the same village, belonging to the same farmer group, or working in a shared community activity. Begin with a manageable number of members who know one another. Groups that expand too quickly may struggle to verify borrowers and resolve disputes.
Hold an initial meeting to discuss membership, savings frequency, maximum loan size, repayment periods, and penalties. Record every decision in simple language. Members should understand that the fund belongs collectively to the group, not to the treasurer or village head.
Build the fund carefully
Regular savings are the foundation of the system. Contributions can be weekly or monthly, with a fixed minimum that matches members’ ability to pay. A modest amount collected consistently is safer than a large target that causes members to drop out or borrow just to make their contribution.
The group may create several financial pools. Basic savings form the lending capital, while a social fund can support illness, bereavement, or other emergencies. If the group charges a service fee on loans, the members should decide in advance whether the income will be distributed, retained as growth capital, or used for group activities.
Keep cash handling limited and transparent. Two authorized people should count money together, and every transaction should be entered immediately in a ledger and confirmed by the member. When possible, deposit funds in a bank or regulated financial account rather than storing large amounts at home.
Set fair lending rules
A loan application should state the amount requested, its purpose, expected repayment source, and proposed schedule. The committee can assess whether the borrower has realistic income, existing debts, and a plan for dealing with poor harvests or slow sales. Character matters, but it should not replace a basic affordability check.
Loan limits are best linked to a member’s savings history and repayment capacity. New members may receive smaller loans, while reliable borrowers can qualify for larger amounts after several successful cycles. Avoid approving loans simply because a member is influential or personally close to a committee officer.
Use written agreements that explain the service fee, due dates, late-payment treatment, collateral if required, and the consequences of default. A guarantor system may work in close communities, but it must be applied consistently. Public humiliation, threats, or confiscation of essential household assets should never be part of debt collection.
Compare practical fund models
Different groups need different arrangements. A short repayment cycle may suit vegetable farmers with frequent harvests, while livestock raisers or small food producers may need longer terms. The group should test a simple model, review its performance after several months, and adjust it through a members’ meeting.
| Fund model | Best suited to | Main strength | Main caution |
|---|---|---|---|
| Fixed weekly savings | Wage earners and small traders | Builds a regular saving habit | Difficult during irregular income periods |
| Seasonal lending | Farmers and livestock raisers | Matches repayment with harvest or sales | Requires careful crop and market assessment |
| Emergency fund | Health, family, and urgent household needs | Provides quick support without high-cost lenders | Must maintain a separate balance |
| Enterprise fund | Food processing, retail, and services | Encourages income-generating activities | Business losses can affect repayment |
| Rotating distribution | Groups seeking periodic lump sums | Gives members access to larger amounts | Provides less flexible credit control |
Village economic activity can benefit when lending is connected to local markets. For example, a group may finance cassava processing, catering, handicrafts, or homestay supplies, while members learn about Indonesian village cuisine to develop food-based products that reflect local identity.
Keep records that everyone can read
At minimum, maintain a membership register, individual savings cards, a cashbook, loan agreements, repayment records, meeting minutes, and a monthly financial summary. Every entry should show the date, member name, amount, purpose, and signature or other acknowledgment.
Separate the duties of chairperson, treasurer, and record keeper. The person receiving money should not be the only person checking the books. At each meeting, announce the opening balance, new savings, loan disbursements, repayments, expenses, and closing balance.
A paper ledger is sufficient for a small group if it is stored safely and updated without gaps. Larger groups can use a spreadsheet or simple bookkeeping application, but digital tools should support—not replace—member verification. Back up electronic records and restrict editing rights to authorized officers.
Manage risk and resolve disputes
Late repayment is easier to manage when the group contacts the borrower early. The committee can offer a revised schedule after reviewing the reason for the delay, but repeated extensions should not hide a bad loan. A loan classification system—current, late, or at risk—helps members see the fund’s real condition.
The group should maintain a reserve for bad debt and emergencies. Do not lend all available capital at once. A cash buffer allows the association to honor withdrawals, respond to urgent needs, and survive a failed harvest or business closure.
Disputes should follow a known process: private discussion with the borrower, review by the loan committee, mediation by trusted community representatives, and a recorded decision by the members’ meeting. Annual elections, periodic audits, and rotation of signatories reduce the risk of favoritism or misuse of funds.
Establish a routine for healthy growth
A strong group improves through regular review rather than rapid expansion. Set a monthly meeting for transactions, a quarterly review for loan performance, and an annual meeting for financial reporting, officer elections, and rule changes. Invite members to ask for explanations without fear of retaliation.
Use these practical safeguards from the first collection:
- Set savings and loan limits that reflect members’ real income.
- Require two-person verification for cash counting and withdrawals.
- Record every transaction on the same day it occurs.
- Link loan approval to repayment capacity and a stated business or household purpose.
- Keep a reserve and review overdue loans before distributing surplus funds.
When the group becomes stable, it can cooperate with a BUMDes, cooperative, bank, agricultural extension service, or local training provider. Such partnerships may improve financial literacy and market access, but the members should retain oversight of their own rules and money.
A village savings and loan group succeeds when its procedures are simple, visible, and consistently applied. Begin with a trusted core membership, document every agreement, lend for productive and necessary purposes, and review the fund openly at every meeting. With disciplined management, small savings can become a durable source of village resilience and opportunity.

Questions or story ideas from your village?
FolderDesa welcomes readers who want to share village experiences or learn more about the topics covered on the site.
Visit the Contact Page