
FolderDesa brings together practical knowledge on farming, village-owned enterprises, culinary traditions, rural tourism, and small-business ideas — all rooted in the everyday life of Indonesian villages.
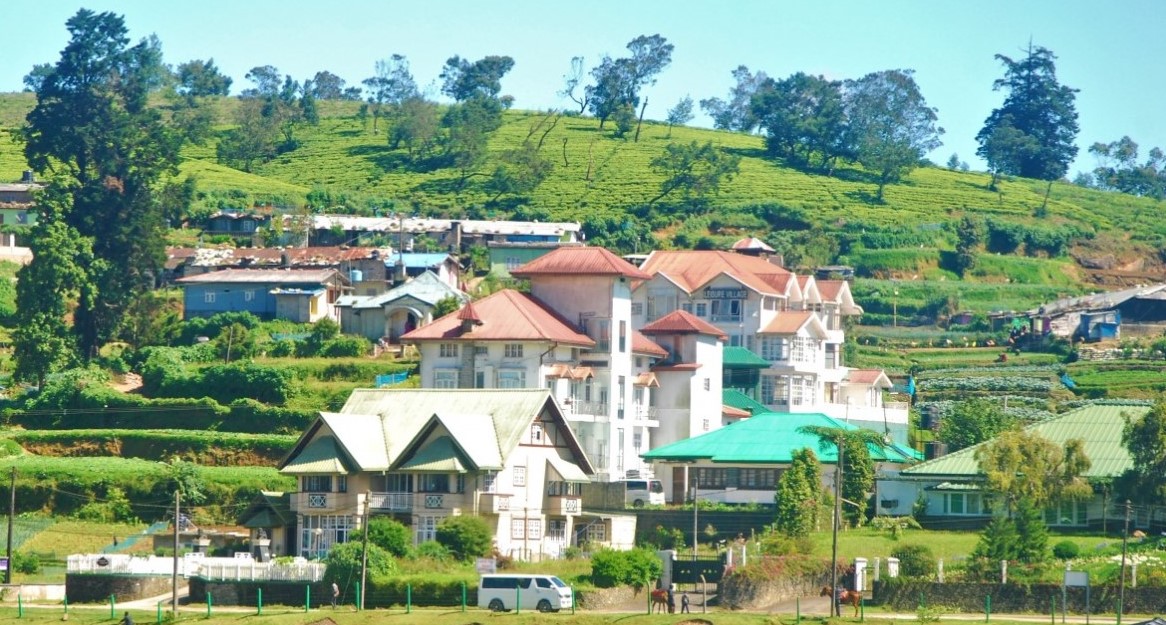
"From taro cultivation in Bogor to village tourism in Banyumas, every village has a story worth telling — and an opportunity worth sharing."
Seven areas of village knowledge
FolderDesa organizes its articles across these interconnected topics, each one grounded in real Indonesian village experience.
What you'll find on FolderDesa
Practical articles written by contributors who understand village life.
Agriculture & Cultivation
Articles on taro (talas bogor), dragon fruit, crystal guava, durian, oyster mushrooms, and tabulampot grapes — plus livestock such as dairy goats and Merino sheep.
Village-Owned Enterprises
Guides on establishing BUMDes, the differences from cooperatives, and why professional phased management matters for village economic growth.
Village Tourism
Coverage of destinations like Desa Karangkemiri in Banyumas, where outbound activities and a swimming pool helped tourism contribute Rp 50 million to village income in 2021.
Culinary Traditions
Indonesian village foods, Sundanese heritage dishes, spiced drinks, infused waters, seafood street-food ideas, and home-industry snack production.
Business Opportunities
From dried wood ear mushrooms and kopyor coconut seedlings to ecoprint crafting, bamboo crafts, and mina padi integrated rice-fish farming.
Village News & Community
Reports on social assistance programs like PKH, village governance structures, and practical tips such as safe homecoming travel during mudik season.
Managing a village credit union through strong BUMDes leadership
A village credit union can help farmers, traders, and household businesses obtain working capital without relying on informal lenders. When it is managed through a healthy BUMDes, the service can keep money circulating within the village while supporting productive activities such as livestock, farming, food processing, and rural tourism.
Successful BUMDes leaders treat village lending as a public trust rather than a quick source of income. They set clear rules, separate business decisions from political interests, and measure success through repayment quality, member welfare, and sustainable profit.
The most effective model combines local knowledge with disciplined financial management. Leaders understand who needs capital, why the money is needed, and which safeguards will protect both borrowers and village funds.
Start with a clear business purpose
A credit unit should have a defined purpose before it begins disbursing loans. The BUMDes board needs to decide whether it will serve farmers during planting season, support microenterprises, finance equipment, or provide emergency household loans. Each purpose requires different repayment periods and risk controls.
A written business plan should include the target members, expected capital, loan products, operating costs, interest or service fees, and a realistic break-even point. It should also explain how the unit will contribute to the village economy instead of competing unfairly with existing cooperatives, banks, or local lenders.
Leaders can strengthen the plan by reviewing village development news and studying nearby BUMDes businesses. Local reports often reveal seasonal problems, commodity prices, infrastructure changes, and opportunities that affect borrowers’ ability to repay.
Build rules that residents can trust
Trust grows when residents understand who may borrow, how applications are assessed, what fees apply, and what happens when payments are late. These policies should be approved through the appropriate village and BUMDes governance process, then explained in meetings and simple written materials.
Loan decisions should involve more than one person. A credit committee can review applications, while the treasurer records transactions and the director monitors performance. Separating these duties reduces fraud, favoritism, and mistakes. Leaders should also require conflict-of-interest declarations when staff or officials have a connection to an applicant.
Confidentiality matters. Community-based lending uses local information, but borrowers should not be publicly shamed or have their financial details discussed casually. Professional treatment encourages honest applications and protects social relationships in the village.
Match loans with village livelihoods
Loan products should reflect the income patterns of residents. A rice farmer may repay after harvest, while a food stall owner may make weekly payments. A livestock borrower may need a grace period before sales generate cash. Uniform monthly installments can create unnecessary pressure when they do not match the borrower’s business cycle.
Before approving a loan, officers should assess the purpose, estimated income, existing debts, household expenses, and proposed repayment source. Site visits are useful for larger loans, especially when financing livestock, machinery, kiosks, or production facilities. The aim is to understand capacity, not to intimidate the applicant.
| Management area | Weak practice | Strong BUMDes practice |
|---|---|---|
| Loan approval | Based on personal connections | Uses documented eligibility and review |
| Repayment schedule | Same schedule for every borrower | Matches farming and business cash flow |
| Financial records | Handwritten notes without review | Daily entries, monthly reconciliation, and backups |
| Delinquency response | Public pressure or sudden penalties | Early contact, restructuring, and written agreements |
| Surplus use | Distributed without a plan | Reserves, village contribution, and business reinvestment |
| Oversight | Informal reporting | Routine reports to directors, supervisors, and the village |
Protect capital with careful monitoring
A credit union can appear profitable while its cash is trapped in overdue loans. For this reason, leaders should monitor repayment rates, outstanding balances, overdue amounts, cash on hand, operating expenses, and the concentration of loans in one sector or group.
Monthly reconciliation is essential. The cash ledger, bank account, loan register, receipts, and borrower balances must agree. Digital bookkeeping can improve accuracy, but staff still need training, password controls, regular backups, and a simple paper contingency system for power or network failures.
A reserve for doubtful loans should be built into the financial plan. When a borrower misses a payment, staff should contact the person early, identify the cause, and document an agreed solution. Rescheduling may be appropriate for a temporary harvest delay, while repeated misuse of funds requires firmer action.
Keep lending compliant and inclusive
BUMDes leaders should confirm the legal structure of their credit service before collecting savings or offering financial products. Depending on the activity, licensing and supervision may involve village enterprise regulations, cooperative rules, or financial-sector requirements. Consultation with the local government, cooperative office, and relevant regulators can prevent costly problems later.
Inclusion should be practical rather than symbolic. Women entrepreneurs, young farmers, informal workers, and residents without conventional collateral may need alternative assessment methods. Cash-flow records, group guarantees, purchase orders, or productive assets can sometimes provide better evidence than land documents alone, provided the arrangement is lawful and clearly documented.
Financial literacy should accompany lending. Short sessions on budgeting, pricing, stock control, and separating household and business money can improve repayment more effectively than strict collection alone. Borrowers who understand their margins are better positioned to use credit productively.
Measure success beyond loan volume
Large disbursement figures do not prove that a village credit union is healthy. BUMDes supervisors should examine the quality of the loan portfolio, the number of active borrowers, repeat repayment behavior, operating costs, member satisfaction, and the income created by financed businesses.
A quarterly public report can summarize capital, total loans, repayments, overdue accounts, surplus, and social benefits without exposing personal borrower information. Transparent reporting gives the village council and residents a basis for oversight and helps leaders identify problems before they become losses.
Practical priorities for BUMDes leaders
- Approve a written lending policy with eligibility rules, limits, fees, collateral options, and collection procedures.
- Separate loan approval, cash handling, bookkeeping, and oversight duties among different people.
- Design repayment schedules around farming seasons and actual business cash flow.
- Review overdue loans every month and contact borrowers before arrears become severe.
- Set aside reserves, maintain accurate records, and publish understandable financial reports.
A village credit union succeeds when it combines empathy with discipline. BUMDes leaders must know the local economy, yet they also need consistent procedures that apply to friends, officials, and first-time borrowers alike. Capital should reach productive activities, repayments should return to the lending cycle, and surplus should strengthen the village enterprise.
For village officials and community members, the next step is to review the current lending rules, records, and overdue accounts together. A simple governance audit can reveal where stronger controls, better training, or redesigned loan products will make the credit service more useful and sustainable.

Questions or story ideas from your village?
FolderDesa welcomes readers who want to share village experiences or learn more about the topics covered on the site.
Visit the Contact Page