
FolderDesa brings together practical knowledge on farming, village-owned enterprises, culinary traditions, rural tourism, and small-business ideas — all rooted in the everyday life of Indonesian villages.
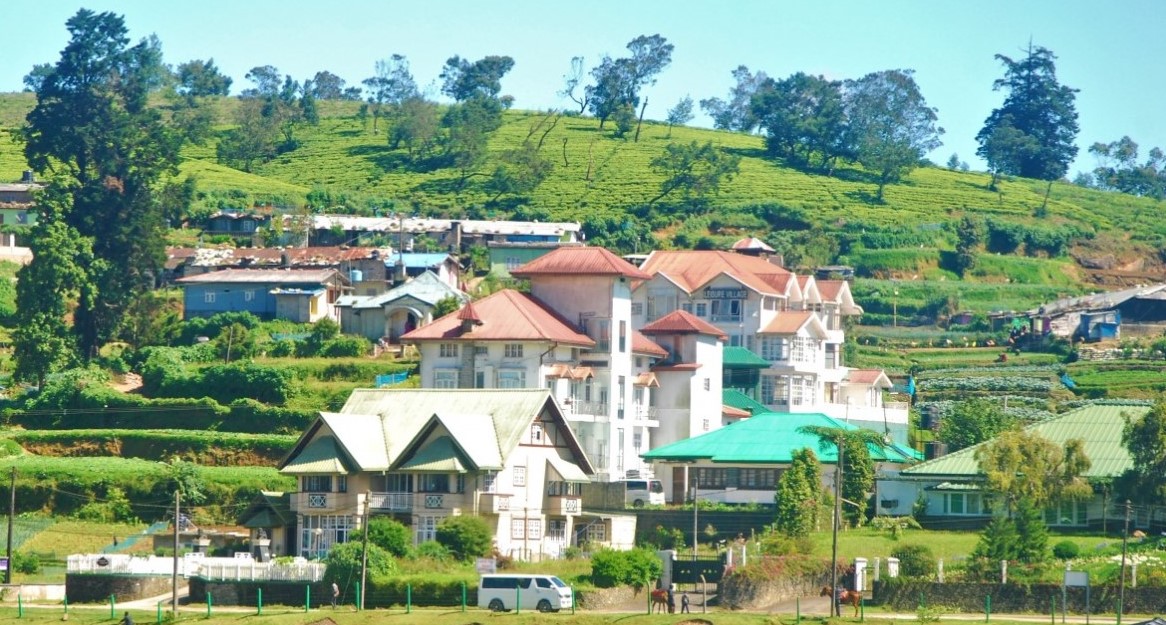
"From taro cultivation in Bogor to village tourism in Banyumas, every village has a story worth telling — and an opportunity worth sharing."
Seven areas of village knowledge
FolderDesa organizes its articles across these interconnected topics, each one grounded in real Indonesian village experience.
What you'll find on FolderDesa
Practical articles written by contributors who understand village life.
Agriculture & Cultivation
Articles on taro (talas bogor), dragon fruit, crystal guava, durian, oyster mushrooms, and tabulampot grapes — plus livestock such as dairy goats and Merino sheep.
Village-Owned Enterprises
Guides on establishing BUMDes, the differences from cooperatives, and why professional phased management matters for village economic growth.
Village Tourism
Coverage of destinations like Desa Karangkemiri in Banyumas, where outbound activities and a swimming pool helped tourism contribute Rp 50 million to village income in 2021.
Culinary Traditions
Indonesian village foods, Sundanese heritage dishes, spiced drinks, infused waters, seafood street-food ideas, and home-industry snack production.
Business Opportunities
From dried wood ear mushrooms and kopyor coconut seedlings to ecoprint crafting, bamboo crafts, and mina padi integrated rice-fish farming.
Village News & Community
Reports on social assistance programs like PKH, village governance structures, and practical tips such as safe homecoming travel during mudik season.
How to launch a village savings and loan group
A village savings and loan group can help residents manage irregular income, fund small businesses, and reduce dependence on informal lenders with high charges. When organized transparently, it becomes a practical community finance service for farmers, traders, workers, and households.
The model is usually built around regular member savings, small loans, shared rules, and collective oversight. It may operate as a community savings group, a cooperative-style association, or a unit connected to a BUMDes, depending on local regulations and its scale.
A successful launch requires more than collecting money. The organizers need a clear purpose, reliable bookkeeping, responsible loan assessment, and a structure that protects both members and the group’s funds.
Identify the local need
Begin by speaking with residents, farmer groups, women’s groups, youth organizations, and microbusiness owners. Ask what financial problems are most common: seasonal farm expenses, school fees, emergency healthcare, working capital, or equipment purchases. These answers should shape the group’s first services.
A village savings and loan group should start with a manageable membership base. Twenty to forty committed members may be easier to serve than a large group with weak participation. Members should live or work in the village, understand the rules, and agree to attend regular meetings.
The group can also support community projects if its members approve them separately. For example, savings may eventually help finance small public works, while technical planning remains distinct; a community footbridge guide can help residents understand why construction costs, safety, and maintenance need their own planning process.
Build a trusted management structure
Elect a chairperson, treasurer, secretary, and loan committee through a members’ meeting. Assign duties clearly so that one person does not control applications, cash, records, and approvals. The treasurer may hold funds, but withdrawals should require two authorized signatures or equivalent approval.
Prepare simple founding documents covering the group’s name, purpose, membership requirements, savings schedule, loan conditions, meeting frequency, profit distribution, and procedures for late payments. If the group is connected to a BUMDes or village government program, clarify ownership and reporting responsibilities in writing.
Check applicable Indonesian rules before accepting public funds, charging fees, or expanding operations. A small member-based group may have different requirements from a formal cooperative or financial institution. Consultation with the village administration, cooperative office, or qualified legal adviser can prevent problems later.
Set practical financial rules
Members need to know exactly how much they must save, how loans are priced, and what happens when payments are late. Keep the first system simple. Weekly or monthly compulsory savings can be combined with voluntary deposits, while loan sizes should be linked to savings history and repayment capacity.
The group should maintain a reserve for unexpected losses and avoid lending all available cash. A written policy can set a maximum loan-to-savings ratio, a service fee, a repayment period, and a limit for emergency loans. Charges should be explained as fixed amounts or clear percentages rather than vague deductions.
| Area | Suggested starting rule | Reason |
|---|---|---|
| Membership | Residents who agree to attend meetings and save regularly | Builds accountability |
| Compulsory savings | A modest fixed amount paid weekly or monthly | Makes participation accessible |
| First loan limit | One to two times a member’s accumulated savings | Controls early risk |
| Repayment period | Three to six months for small productive loans | Keeps money circulating |
| Late payment | Written reminder, meeting review, and agreed restructuring | Encourages repayment without humiliation |
| Reserve fund | A portion of surplus retained each period | Protects the group from losses |
All rules should be approved in a recorded members’ meeting. If the community changes the savings amount, interest or service fee, or loan ceiling, record the decision and its effective date.
Create records that everyone can follow
Use a member ledger, savings book, loan register, cashbook, receipt book, and bank or cash reconciliation sheet. Each deposit and repayment should produce a receipt or signed record. Digital spreadsheets can help, but paper records remain useful where internet access, devices, or electricity are unreliable.
At every meeting, report opening cash, deposits, loan disbursements, repayments, expenses, overdue balances, and closing cash. Two people should count money together, and the result should be signed. Monthly reconciliation can reveal missing entries before they become serious losses.
Transparency does not mean publishing private member information. Share group-level figures openly while limiting personal details to authorized officers. A quarterly review committee made up of members who are not daily managers can check cash, records, and outstanding loans.
Assess loans and manage repayment
Loan applications should state the purpose, amount, repayment schedule, and proposed source of repayment. Productive uses such as seeds, livestock feed, food processing equipment, or small-shop inventory may generate income, but the committee should still examine the applicant’s existing obligations and household cash flow.
Avoid approving loans simply because an applicant is popular or related to an officer. Use the same basic criteria for every member. For larger loans, request a guarantor, collateral that is legally and ethically appropriate, or a group guarantee approved by members.
Late repayment should be addressed early. Contact the borrower respectfully, understand whether the problem is temporary or structural, and record any revised schedule. Repeated delays may require smaller future loans, a temporary suspension, or mediation through the membership meeting. Public shaming can damage trust and reduce honest communication.
Launch with disciplined first steps
A short pilot period allows the group to test its systems before expanding. Start with member savings, a small number of loans, and frequent reviews. Do not use outside grants or village funds to hide weak repayment practices; additional capital should follow evidence of sound management.
Use these priorities during the first three months:
- Confirm the member list, elected officers, and written operating rules.
- Open a secure account or establish dual-control cash procedures.
- Train officers to issue receipts, update ledgers, and reconcile balances.
- Approve only loans with clear purposes and affordable repayment schedules.
- Publish a simple monthly financial report for all members.
At the end of the pilot, review participation, savings growth, repayment performance, administrative costs, and member complaints. The results can guide decisions about adding business loans, emergency loans, or a partnership with a BUMDes.
Keep trust at the center
Money moves quickly through a close village community, so trust is the group’s most valuable asset. Leaders should disclose conflicts of interest, refuse preferential treatment, and respond to concerns before rumors spread. Members should also understand that savings are a shared responsibility, not an automatic source of cash.
A well-run group can strengthen household resilience and support village enterprises without becoming overly complicated. Begin with a clear purpose, modest amounts, careful records, and regular member oversight. Gather the founding members, approve the rules, and hold the first savings meeting with transparency from the first transaction.

Questions or story ideas from your village?
FolderDesa welcomes readers who want to share village experiences or learn more about the topics covered on the site.
Visit the Contact Page