
FolderDesa brings together practical knowledge on farming, village-owned enterprises, culinary traditions, rural tourism, and small-business ideas — all rooted in the everyday life of Indonesian villages.
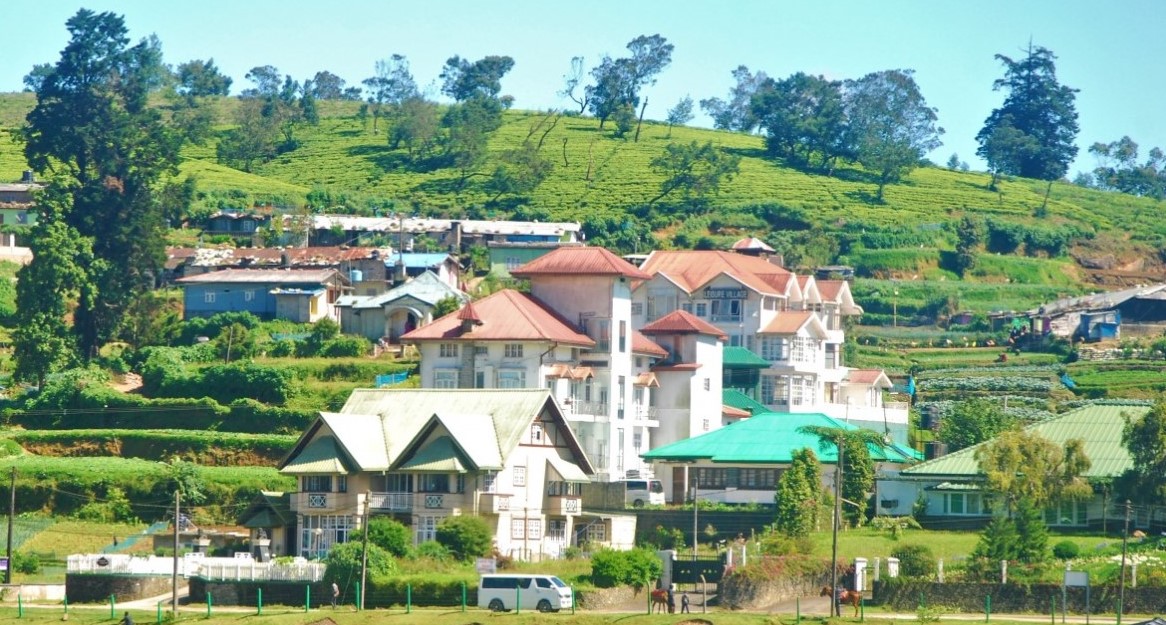
"From taro cultivation in Bogor to village tourism in Banyumas, every village has a story worth telling — and an opportunity worth sharing."
Seven areas of village knowledge
FolderDesa organizes its articles across these interconnected topics, each one grounded in real Indonesian village experience.
What you'll find on FolderDesa
Practical articles written by contributors who understand village life.
Agriculture & Cultivation
Articles on taro (talas bogor), dragon fruit, crystal guava, durian, oyster mushrooms, and tabulampot grapes — plus livestock such as dairy goats and Merino sheep.
Village-Owned Enterprises
Guides on establishing BUMDes, the differences from cooperatives, and why professional phased management matters for village economic growth.
Village Tourism
Coverage of destinations like Desa Karangkemiri in Banyumas, where outbound activities and a swimming pool helped tourism contribute Rp 50 million to village income in 2021.
Culinary Traditions
Indonesian village foods, Sundanese heritage dishes, spiced drinks, infused waters, seafood street-food ideas, and home-industry snack production.
Business Opportunities
From dried wood ear mushrooms and kopyor coconut seedlings to ecoprint crafting, bamboo crafts, and mina padi integrated rice-fish farming.
Village News & Community
Reports on social assistance programs like PKH, village governance structures, and practical tips such as safe homecoming travel during mudik season.
Digital payments for Indonesian village shops
Village shops in Indonesia often combine cash, informal credit and face-to-face trust. A digital option can record sales and widen customer choice without forcing every trader to stop handling notes and coins.
A practical village digital payment system should sit alongside existing habits. This approach uses QRIS-compatible apps, a cooperative or BUMDes settlement account, and simple paper receipts, giving merchants a gradual path to digital transactions.
Australian readers will recognise the mixed habits: many Sydney and Melbourne counters accept contactless cards and phone wallets, while delis, roadside produce sellers and farmers markets still need cash. The lesson is to combine familiar payment rails with trusted local service.
Begin with the village economy
Start by recording how money moves through each shop. Farmers may receive cash from a collector, market traders may transfer wholesale payments, and customers may buy ingredients in small amounts. Each transaction has a different value, frequency and settlement pattern.
Tourism can increase foot traffic, and village walking trails can bring visitors into local cafés, stalls and homestays. Merchants near these routes could begin accepting digital payments through a shared cooperative account rather than opening individual accounts with complex terms.
The operating entity needs a clear purpose. A BUMDes, cooperative or merchant association can issue merchant codes, collect service fees and fund shared equipment. It should also publish who can approve transfers, how revenue is distributed and how shopkeepers can query a disputed payment.
Design a payment flow people trust
The customer journey should fit on one screen. A printed counter QR code can open a payment request, while a dynamic code can include the order value for higher-value purchases. Customers then confirm the recipient, amount and PIN through their banking or e-wallet application.
Shopkeepers need an equally simple confirmation method. The application can show a green payment marker, transaction reference and optional receipt. For rural areas with unreliable connectivity, the service should record payments for later synchronisation, with a clear rule against asking a customer to pay twice.
Australia’s PayID and BPAY services provide a useful benchmark because speed depends on familiar confirmation and reconciliation. A village service should offer comparable clarity: a unique reference, visible transaction status and a direct channel for reporting errors. Cash must remain available during outages or for customers who do not use digital wallets.
Build technology around existing habits
Most shops do not need custom software. An authorised provider can supply a shared platform, Android applications, QR codes and settlement reports, while the cooperative manages participation and local rules. A browser-based dashboard would also help officials review activity without installing specialist accounting systems.
The interface should reflect the character of each business. The same care shown in vintage shop displays can make a counter feel current without erasing its local identity. Payment prompts can sit beside handwritten price cards, familiar product photographs and receipts.
Connectivity and literacy require practical safeguards. Mobile coverage is generally strong around Indonesian towns and major Australian cities, but rural and remote areas can experience interruptions. USSD or voice confirmation may help customers with limited smartphone access, while staff training should cover PIN security, recognising fake payment requests and reconciling the day’s takings against the bank settlement report.
Set safeguards for money and data
The cooperative should use an authorised Indonesian bank or fintech partner rather than create an informal transfer pool. Merchant registration, customer identification and transaction monitoring must follow the provider’s regulatory framework. Settlement funds should remain in a properly governed cooperative or BUMDes account, with dual approval for withdrawals and a monthly statement available to participating shops.
Data collection should be limited to what the service genuinely needs. A shopkeeper’s identity, contact details, bank details and transaction history may be required for onboarding and reconciliation, but household purchases should not be analysed for advertising. Access to records should be restricted by role, and personal data should not be shared with local officials without a lawful purpose.
An Australian technology or funding partner may need to meet obligations under the Privacy Act 1988, Australian Consumer Law and AUSTRAC rules, depending on its role. Consumer-facing services should explain fees, refund conditions and payment limits in plain language. Clear signs showing a digital payment option, its fee and the available cash alternative help prevent misunderstandings at the counter.
Pilot, measure and expand
A small pilot should test the complete flow, not merely register QR codes. Select three contrasting businesses—a grocery seller, a market trader and a food stall—and record cash transactions, digital payments, settlement times, support requests and reconciliation errors before and after launch.
The service can become one of the local business opportunities supported by the village economy. Revenue might come from a transparent transaction fee, merchant subscriptions or a share of cooperative services. Shopkeepers should receive a monthly statement showing gross payments, deductions, settlement dates and any corrections.
Expansion should depend on evidence rather than enthusiasm. The cooperative can recruit more shops when payment success rates remain high, failed transactions are resolved quickly and merchants report meaningful benefits. Training, printed signs, replacement devices and a support contact must be ready before participation grows.
A practical comparison clarifies the trade-offs.
| Feature | Cash and paper ledger | Shared digital payment system | Australian benchmark |
|---|---|---|---|
| Setup | Almost immediate and inexpensive | Requires codes, devices and onboarding | Tap-to-pay terminals are familiar in cities |
| Customer choice | Cash only | Cash, QR wallets and banking apps | Cards, PayID and BPAY support multiple options |
| Record keeping | Manual and prone to omissions | Timestamped records with daily reconciliation | Digital receipts and automated payment reports |
| Main risk | Errors, theft and weak sales data | Fees, fraud and connectivity failures | Consumer-law, privacy and AML controls apply |
| Resilience | Works without power or connectivity | Requires a cash fallback during outages | Contactless systems still need outage procedures |
The next step is a 14-day pilot with three shops, one cooperative settlement account and daily reconciliations, followed by one review of fees, failed payments, cash usage and merchant feedback before expansion.

Questions or story ideas from your village?
FolderDesa welcomes readers who want to share village experiences or learn more about the topics covered on the site.
Visit the Contact Page